Need help? Talk to an expert
Only a small group of lenders offer SMSF loans. Each one has its own rules regarding trustee type, fund balance, and loan size.
Working out which lender is the right fit for your fund is the hard part.
Guessing can cost you weeks, but with an SMSF loan broker on your side, you don’t have to work it out alone.
Oscar&Charles is a Williamstown finance brokerage with 20+ years of experience in the mortgage industry. We know which lenders on our panel of 90+ lend to SMSFs, and which of them best suit your fund.
We arrange SMSF loans for commercial property, including premises your business already occupies, and we also help refinance existing SMSF loans. In addition, we check loan structures, coordinate the paperwork, and keep your accountant and solicitor in the loop.
Wherever your fund is located in Australia, we’re the SMSF mortgage brokers you can rely on from start to finish. Think of us as the people who read the lender fine print, manage the paperwork, and handle everything in between, so you don’t have to.
0411 825 257
We’ve worked through several rule changes and lender shifts, helping guide you towards the right solution.
We match you with the right lenders, so your fund isn’t forced to fit within a single lender’s rules.
Whichever state your fund is in, we can help with SMSF refinances and commercial loans.
Want to speak with an SMSF loan broker in Australia? Justin’s the right person to help get your funding.
Few lenders offer SMSF lending, and each has its own rules.
Oscar&Charles is an SMSF mortgage broker that can steer you towards the lenders most likely to approve your application. Here’s how we do it:
Our panel includes 90+ lenders, and we know which ones lend to SMSFs and which may be the best fit for your fund. We also understand how each lender assesses trustee structure, fund balance, and loan size. That means your application is more likely to reach the right lender first, rather than the fifth.
We spot trustee, trust deed, and lease issues before a lender does. A trust deed that does not allow borrowing or a lease that is not at market rent can derail an application. If something needs fixing, we'll help you sort it out before the application is submitted.
We'll outline the deposit, stamp duty, legal fees, and bare trust costs before you commit. Because an SMSF must pay these expenses from the fund's own cash, there is little room for surprises. Your accountant can then review each figure against the fund's cash flow.
The 2026 changes reshaped what a fund can borrow for. We keep track of those changes for you and explain what they mean for your fund in plain English. That gives you a clear understanding of your options before you commit to anything.
We work alongside your accountant, solicitor, and adviser to ensure every aspect of the funding process is covered. They handle the tax, legal, and investment considerations, while we look after the lending. Throughout the process, we keep everyone informed and up to date.
One SMSF mortgage broker manages the application and lender enquiries from start to finish. That means you'll deal with the same person from the first call through to settlement, without having to explain your fund's story to someone new at every stage.
Quick note: “SMSF broker” sometimes refers to a share broker who trades on behalf of your fund. Oscar&Charles is an SMSF broker for loans only. We do not buy or sell shares. If you’re searching for an SMSF loan broker, that’s us.
As SMSF mortgage brokers, we mean it when we say we take care of you from the first call right through to settlement. We keep you up to date at each stage, so you always know where you are in the process.
Give us a call or reach out to us through the form below. Tell us about your fund and the property or loan you have in mind. We’ll tell you straight what is possible and what isn’t.
We look at your fund’s structure, including the trustee, trust deed, and investment strategy. If a property is involved, we check whether it qualifies as business real property. If any issues arise, we’ll help you fix them.
From our panel of 90+, we shortlist the lenders that do SMSF loans and explain the trade-offs in plain English. This helps you see which option offers the best fit for your situation.
We provide a checklist tailored to your situation, prepare the application, and handle the lender’s questions. We’ll keep your accountant and solicitor in the loop as well, if needed.
Your solicitor sets up the bare trust and reviews the loan documents, while the lender arranges the valuation and formal approval. We chase up any loose ends so nothing gets left behind.
At Oscar&Charles, the job doesn’t end once the lender approves the application. We stay with the deal until settlement, or until your refinance is complete. After that, we’re still only a phone call away.
Quick note: “SMSF broker” sometimes refers to a share broker who trades on behalf of your fund. Oscar&Charles is an SMSF broker for loans only. We do not buy or sell shares. If you’re searching for an SMSF loan broker, that’s us.
When it comes to SMSF commercial loans, the property generally needs to qualify as business real property, meaning land and buildings used wholly and exclusively for business purposes.
Not sure where your situation fits? Here are some common scenarios:
Looking to use an SMSF loan to purchase a property? From 10 August 2026, a new SMSF loan can only fund business real property. Residential property is off the table, and business real property is available if the property qualifies.
Already have an SMSF loan in place? If you took it out before 10 August 2026, it can continue. That applies whether the property is residential or business real property.
Looking to refinance an SMSF property loan? You can refinance a loan taken out before 10 August 2026 for either kind of property. Lenders set their own conditions.
If your fund exchanged a binding contract before that date, the old rules still apply, even if settlement falls later. We’ll help you check how that works for your situation.
If your SMSF has sufficient funds available, purchasing a property outright may be an option. Business real property can often be acquired this way, while residential property purchases must comply with SMSF regulations and your fund’s investment strategy.
Still not sure where your plans fit? Get in touch with us, and we’ll help you understand your options.
Already have an SMSF loan and want to refinance it?
Oscar&Charles can help.
You can refinance an SMSF loan you took out before 10 August 2026, whether the property is residential or business real property. The ATO counts a refinance as a new loan contract for the same property.
Looking for SMSF home loan brokers to review a residential loan your fund already holds? Reach out with your situation, and Justin will walk you through your SMSF loan refinance options, wherever you are in Australia.
Justin is an SMSF mortgage broker based in Williamstown, Melbourne.
He handles SMSF loans in Melbourne and SMSF lending for funds across Australia. Not every Melbourne mortgage broker does SMSF work. Justin does. He also has a team behind him that has been arranging finance for clients for more than 20 years.
SMSF lending in Melbourne requires an understanding of the property, the lease, and the fund. Justin has experience with all three and reviews each one before submitting an application to the lender.
Looking for Melbourne SMSF loans for business real property? It could be the premises you already operate from or a new property. Justin is the broker to call.
Justin helps individual trustees through every step of an SMSF commercial property loan, from the first call through to settlement. He checks the structure, matches the fund with a suitable lender, prepares the application, and keeps your accountant and solicitor in the loop.
To get started, simply bring the property address and lease details, and we’ll take it from there.
Prefer to talk face to face? Book a time through the form below and visit Justin at our Williamstown office. If not, a virtual meeting works too.
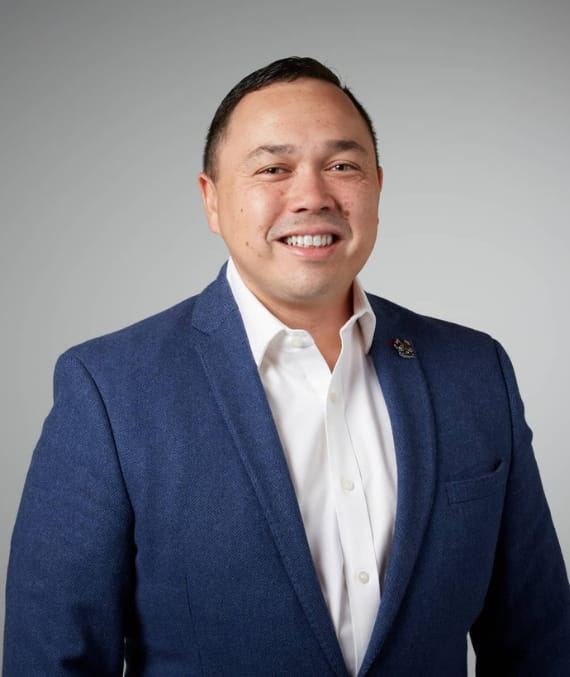
Your fund doesn’t need to be in Melbourne for Justin to help. As an SMSF loan broker helping funds across Australia, he arranges SMSF loans nationwide through a panel of 90+ lenders and knows which ones lend to SMSFs.
Curious about what a loan could cost your fund each month? Enter the loan amount, interest rate, and loan term into our loan repayment calculator and see your estimated repayments in seconds.
The results are a guide only. SMSF lenders assess the entire fund, and Justin can review your actual numbers during a free call.
An SMSF loan allows your self-managed super fund to borrow money to purchase a property. The fund borrows through a Limited Recourse Borrowing Arrangement (LRBA), a structure designed specifically for SMSF property lending.
Since 10 August 2026, a new SMSF loan can only be used to fund business real property. The loan structure has four key components:
Before approving a loan, lenders assess whether the fund can comfortably service the debt. They typically consider rental income, the fund’s balance, expected contributions, and the trustee structure.
The trustee type matters, too. A corporate trustee is a company that acts as trustee for the fund, while under an individual trustee structure, the members act as trustees themselves. Some lenders will only lend to funds with a corporate trustee.
Ask any SMSF loan mortgage broker, and you’ll likely hear the same advice to get the structure right from the start. Fixing it later is usually more complicated and can cost more.
From 10 August 2026, an SMSF can no longer take out a new LRBA to buy residential property.
Instead, a new SMSF loan can only be used to fund business real property.
However, three important things remain the same. First, loans that were already in place before that date can continue, and funds are not required to unwind them. Second, a contract exchanged before 10 August 2026 can still proceed under the old rules, even if settlement occurs later. Lastly, existing SMSF loans can still be refinanced, although lenders will set their own conditions.
If you’d like to know more about these changes, you can reach out to Justin through the form below.
For the full detail, read the ATO’s guidance on the LRBA changes.
We last reviewed this answer in October 2026.
Generally, no.
Starting 10 August 2026, an SMSF can no longer take out a new LRBA to buy residential property.
However, SMSF loans that were already in place before that date can continue and may still be refinanced. Likewise, a contract exchanged before 10 August 2026 can still proceed under the old rules, even if settlement occurs later.
An SMSF may also be able to buy residential property using its own funds, provided the purchase complies with superannuation rules and the fund’s investment strategy.
Before making any decisions, it’s a good idea to speak with an SMSF mortgage broker about your specific circumstances.
Yes, provided the property qualifies as business real property.
This generally means land and buildings that are used wholly and exclusively for business purposes.
It’s important to note that commercial zoning alone is not enough to qualify a property, and mixed-use properties require additional consideration. The property must also continue to meet the business real property requirements for the duration of the loan.
Before signing a contract, check with your accountant or an SMSF specialist that the property meets the requirements. Justin can then confirm whether it suits a lender’s policy.
Yes!
You can still refinance an existing SMSF loan, including a residential property loan your fund took out before 10 August 2026.
However, lenders set their own refinancing conditions. In many cases, they require the new loan to repay the existing loan and cover any refinance costs, without releasing additional cash from the fund.
Oscar&Charles will compare SMSF lenders, explain the trade-offs, and help you find the option that best suits your fund.
We start by reviewing your existing loan, including the lender, interest rate, loan term, and trust structure.
From there, we compare it with lenders on our panel that offer SMSF refinancing.
When the refinance settles, the new loan repays the old one.
In most cases, the property and bare trust remain in place, while the lender and loan terms change.
Many people refinance to secure a lower rate, a better loan structure, or a lender that’s easier to deal with. Our mortgage refinancing covers this service in more detail.
Things to keep in mind: Lenders set their own refinancing conditions. In many cases, they require the new loan to repay the existing loan and cover the refinance costs. Many lenders also won’t release cash or fund another asset as part of the refinance.
When assessing an SMSF refinance, lenders look at how the existing loan has performed.
Some ask for six to twelve months of repayment history and also review the fund’s balance, the property, and any lease arrangements.
The trustee structure matters too. That’s why some lenders require a corporate trustee, and having a current investment strategy and up-to-date audit records can help speed up the assessment process.
Good to know: If your fund doesn’t already have a loan and you’re looking to borrow for a new residential property purchase, that option is no longer available. We’d rather tell you now than after you’ve paid for a valuation. The main exception is where a contract was exchanged before 10 August 2026, in which case the previous rules may still apply.
Only a small group of lenders offer SMSF loans.
Many are specialist lenders, and each has its own requirements around loan size, trustee type, and fund balance.
While you can approach lenders directly, an SMSF mortgage broker can save you from guessing which door to knock on. Our panel includes 90+ lenders, and we know which ones are most likely to suit your fund and circumstances.
It depends on the lender, the property, and the fund.
Every lender sets its own rules, so treat the ranges below as a guide rather than a guarantee. But here’s a sure thing: We’ll confirm the current lending policy for your fund before making any recommendations.
When assessing an SMSF loan application, lenders typically look at the following:
SMSF loan interest rates change regularly, which is why we don’t publish them here.
In general, SMSF loan rates tend to be higher than standard home loan rates, with commercial SMSF loans often priced higher again.
The rate you’re offered will depend on several factors, including the lender, the loan-to-value ratio, the property, and the overall strength of the fund.
If you’d like an up-to-date indication of rates, give us a call or reach out to us through the form below. Justin will provide current options based on your situation.
Yes, provided the premises qualify as business real property.
In fact, buying the premises your business already operates from is one of the most common reasons an SMSF borrows.
When structured correctly, your business pays rent to the SMSF, allowing that income to flow into your fund rather than to a third-party landlord. However, there are a few important rules to keep in mind:
Before signing a contract, it’s best to have your accountant or SMSF specialist confirm that the structure meets all relevant requirements.
A commercial SMSF mortgage broker helps bridge the gap between your advisers and the lender. Oscar&Charles Finance Group (OCFG) reviews the lease details, valuation approach, and trustee structure early in the process, so lenders have fewer reasons to delay the application.
If your business also needs finance of its own, our commercial finance brokerage covers that side as well.
The exact requirements vary between lenders, but most will ask for a combination of these:
Depending on your circumstances, the lender may request additional documents. To make the process easier, we provide a checklist tailored to your specific situation.
The timeline for an SMSF loan depends on the lender, the property, and how organised your paperwork is.
In fact, tidy paperwork is often the cheapest way to speed up the process.
Once we know the lender and the property involved, we can give you a realistic timeline based on your situation.
The costs will typically include the bare trust setup, legal fees, a valuation, lender fees, and stamp duty on a purchase. If you’re refinancing, there may also be exit fees and new setup costs to consider.
Got a property in mind or a loan you’d like to refinance? Tell us where you’re at, and we’ll give you a straight answer about what’s possible with your SMSF loan.
We never charge for calls, and we provide honest lending advice from day one.
Searching for an SMSF mortgage broker near you? If you’re in Melbourne’s west, we’re just around the corner. If you’re anywhere else in Australia, we’re only a phone call away.
Just give us a call on 0411 825 257.